 List (.pdf)

The UK resident company is a junior partner in an enterprise controlled and managed outside the UK, and its activity is limited to issuing invoices according to instructions from the offshore partner. The amount of taxation depends on the partnership share; for example, 5% means a tax rate of 1.2% (i.e. 5% of 24%).
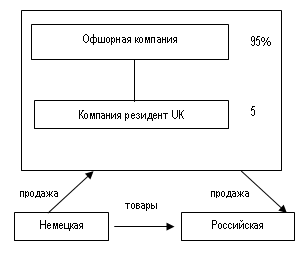
Partnership agreements are confidential.
The partnership itself is not taxed in the UK and may have its own VAT number.
Only tax on the UK company’s share.
The structure is approved by the tax authorities.
Clients interested in using UK structures can contact a professional consultant of Offshore Express LLC.